
The rapid gains of previous decades could become less common, with new Cotality analysis suggesting homeowners may need to rethink their long-term expectations.
The rolling 10-year growth rate for New Zealand’s national median property value has recently fallen to a historically low level.
As mentioned in the previous story, national property values have increased at an average annual rate of 3.2% over the past decade. However, that is well below the long-term annual growth rates of 6–7% seen in previous decades.
Cotality Chief Property Economist Kelvin Davidson said several factors could explain why future price growth might be more restrained.
Why might property prices grow more slowly?
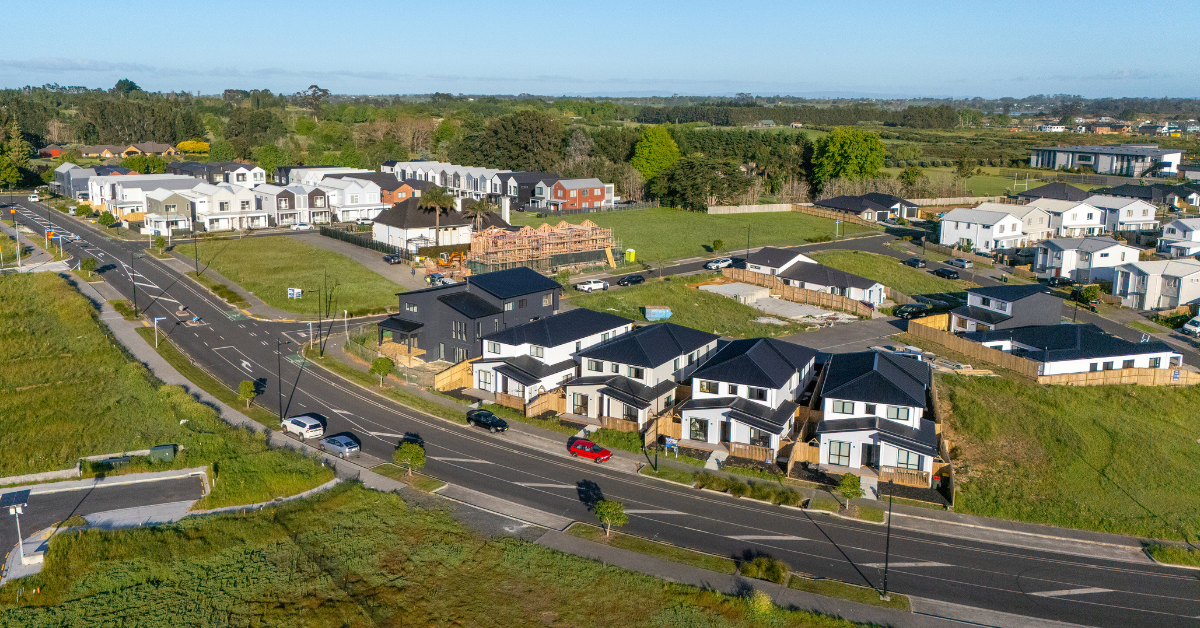
One factor is housing supply. In Auckland, for example, the number of homes has grown faster than the population since 2018, helping to ease some of the pressure that previously pushed prices higher.
Another factor is interest rates. Over several decades, mortgage rates fell substantially from historical highs, allowing buyers to borrow more and helping drive property prices upwards. With that long-term decline already having occurred, the same boost to borrowing power may be harder to repeat.
Other factors include debt-to-income restrictions, which limit how much some borrowers can borrow relative to their earnings, and the possibility of less favourable property tax rules in future.
Together, these changes could mean property prices become more closely linked to household income growth.
What could this mean for homeowners?
Mr Davidson suggested that long-term annual property price growth could shift from the historical 6–7% range towards something closer to 3–5%.
However, he stressed that this would not rule out periods of stronger growth. Rather, it would mean homeowners and investors should be cautious about assuming past growth rates will continue indefinitely.
For buyers, the findings are a reminder that purchasing decisions should be based on affordability and personal circumstances, rather than expectations of rapid capital gains.
Property is a long-term commitment, so it’s important to understand the numbers beyond the purchase price. I’d be happy to talk you through your loan options and what your repayments could look like over time.